Claims We Handle
Whatever caused the loss, the work starts the same way: we read your policy, document the damage, and build the claim your policy supports.
Fire Damage
Structural fire loss, documented room by room.
Learn More about Fire Damage
Smoke Damage
Soot, odor, and smoke that reached rooms the fire never touched.
Learn More about Smoke Damage
Water Damage
Leaks, appliance failures, and flooding, with full drying and repair scopes.
Learn More about Water Damage
Storm Damage
Lightning, rain intrusion, and broad damage from severe storms.
Learn More about Storm Damage
Wind Damage
Lifted shingles, torn siding, and wind-driven rain damage.
Learn More about Wind Damage
Hurricane
Wind and water losses after major coastal and inland storms.
Learn More about Hurricane
Hail Damage
Bruised shingles, dented metal, and exterior damage from hail.
Learn More about Hail Damage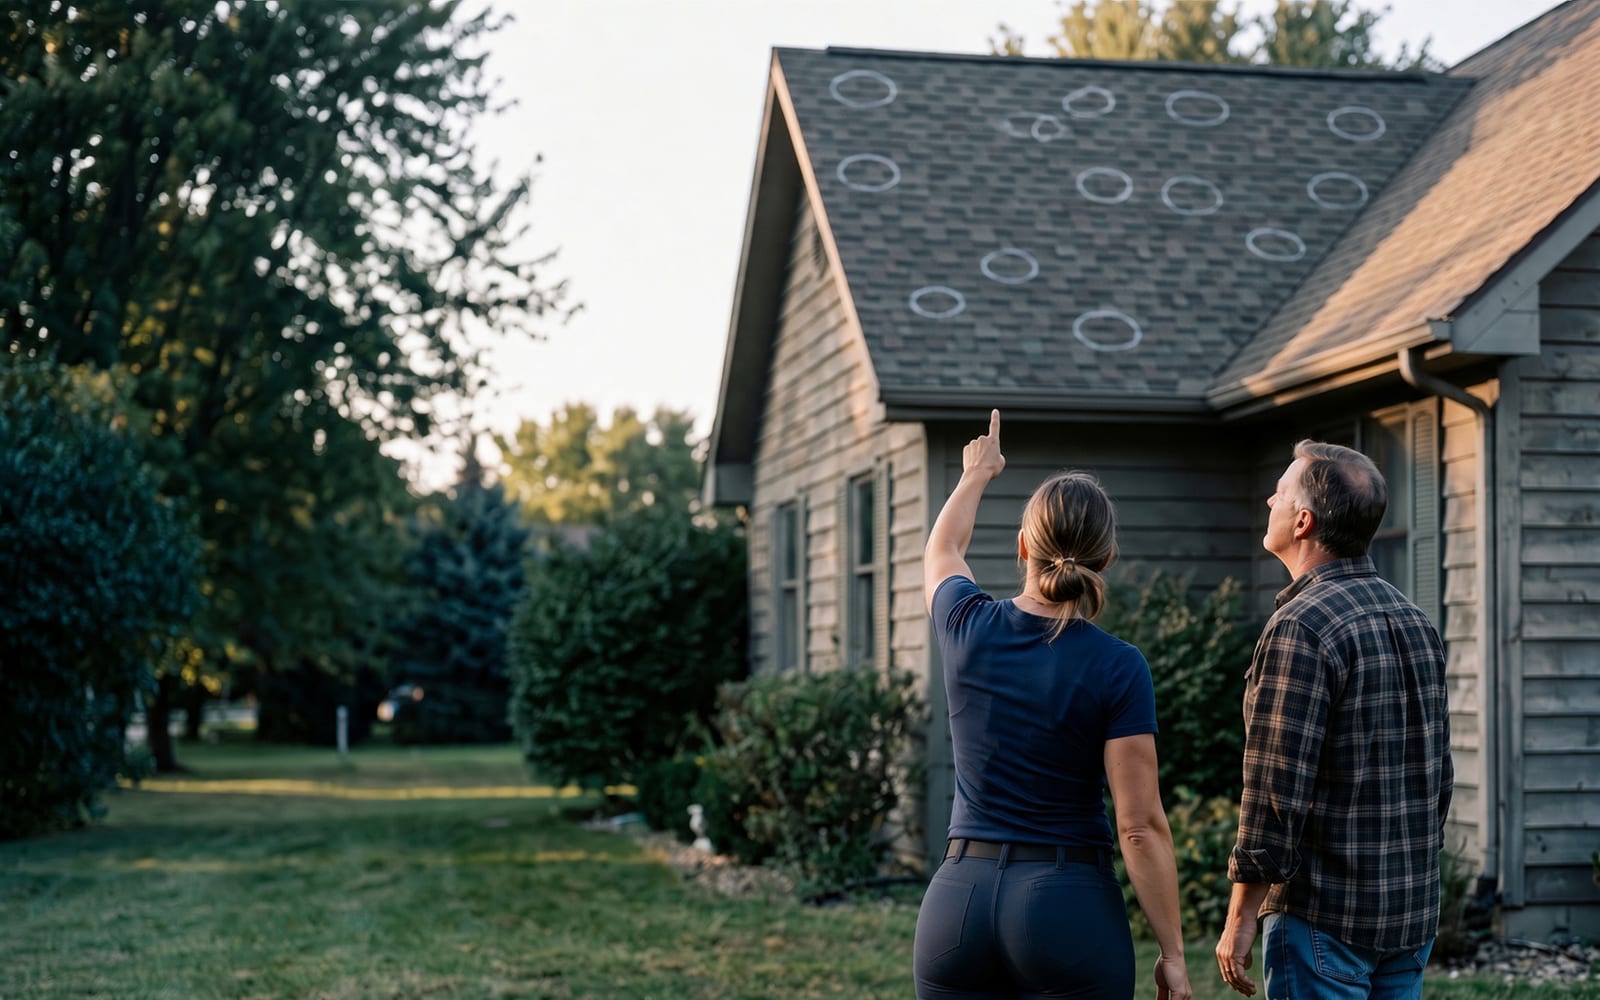
Roof Damage
Roof repair and replacement disputes, from leaks to full replacement.
Learn More about Roof Damage
Tree Damage
Fallen trees and limbs, with the damage and removal costs they cause.
Learn More about Tree Damage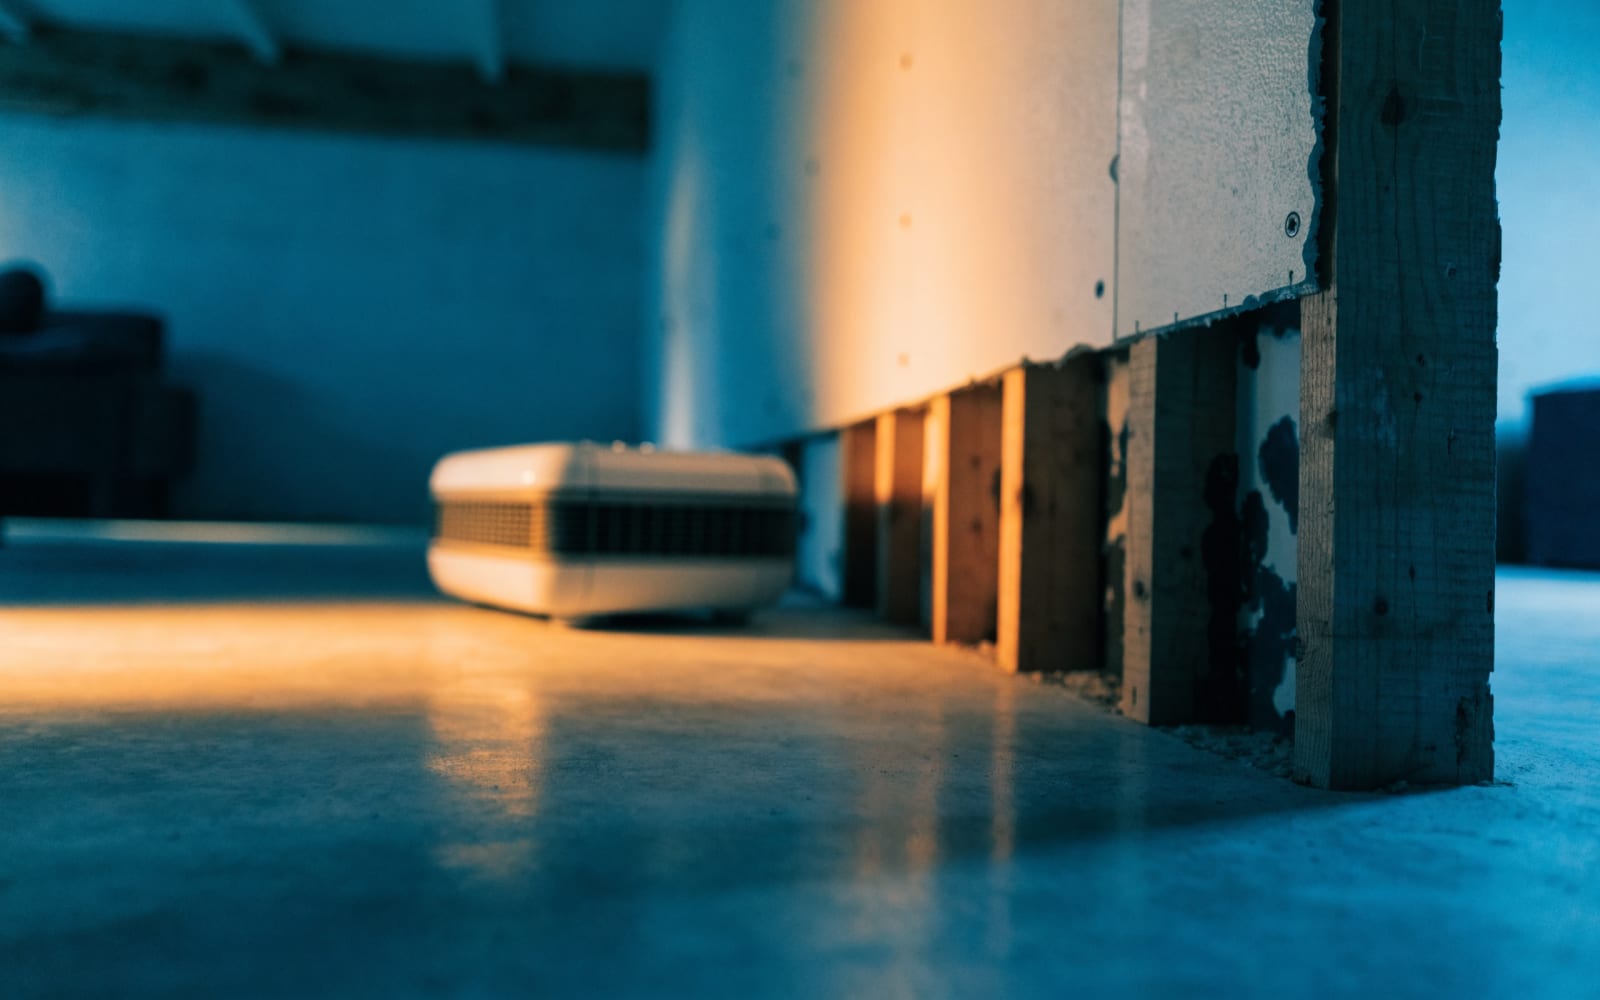
Mold
Hidden moisture, visible growth, and the testing and remediation limits in your policy.
Learn More about Mold
Frozen Pipes
Burst and split pipes, freeze damage, and the water loss that follows.
Learn More about Frozen Pipes
Commercial
Property and business interruption losses for owners and landlords.
Learn More about Commercial
Residential
Full-loss claims for houses, condos, and rental dwellings, from first photo to final payment.
Learn More about Residential
Denied Claims
A second look at denial letters, the policy language cited, and the reasons given.
Learn More about Denied Claims
Underpaid Claims
Lowball offers, missed line items, and estimates that fall short of real repair costs.
Learn More about Underpaid Claims
Vandalism
Break-ins, theft, and malicious damage, documented for your insurer.
Learn More about VandalismHow We Can Help
Beyond the type of loss, you can work with us in the role that fits your situation. Available in GA, TN, SC & NC.
Public Adjuster
We represent you, not the insurer, from first photo to final settlement.
Learn More about Public Adjuster
Appraiser
We serve as your appraiser when your policy's appraisal clause is invoked.
Learn More about Appraiser
Umpire
We act as a neutral umpire when appraisers cannot agree on the amount of loss.
Learn More about UmpireDenied Or Underpaid?
A denial or a low offer is not always the last word. We check what the insurer decided against what your policy says.
Already Filed? Bring These Three Things
- Your policy and declarations page
- Any denial or estimate letters from your carrier
- Photos and videos of the damage
How It Works
- 01
Free Claim Review
Tell us what happened. We review your policy and claim status at no cost.
- 02
Inspect & Document
We photograph, measure, and record every area of loss.
- 03
Build & Negotiate
We prepare the estimate and negotiate with your insurer on your behalf.
- 04
Get Paid Fairly
We push for the full value of your claim, then help you move forward.
Questions, Answered
Which Types Of Claims Do You Handle?
Fire, smoke, water, storm, wind, hurricane, hail, roof, tree, mold, frozen pipe, residential, commercial, vandalism, denied, and underpaid claims.
Do You Handle Commercial Claims?
Yes. We work on property and business interruption losses for owners of homes, rentals, condos, and commercial buildings.
What Should I Do Right After Damage?
Make the property safe, photograph the damage before cleanup, keep your receipts, and report the loss to your insurer. Then call us before you accept any offer.
How Long Does A Claim Take?
It depends on the loss and the insurer. We explain the likely timeline during your free claim review.