Hurricane Damage Claims
Hurricanes bring wind, rain, and flooding at once, and policies treat each differently. We separate the damage by cause and build the claim around your coverage.
What We Look For
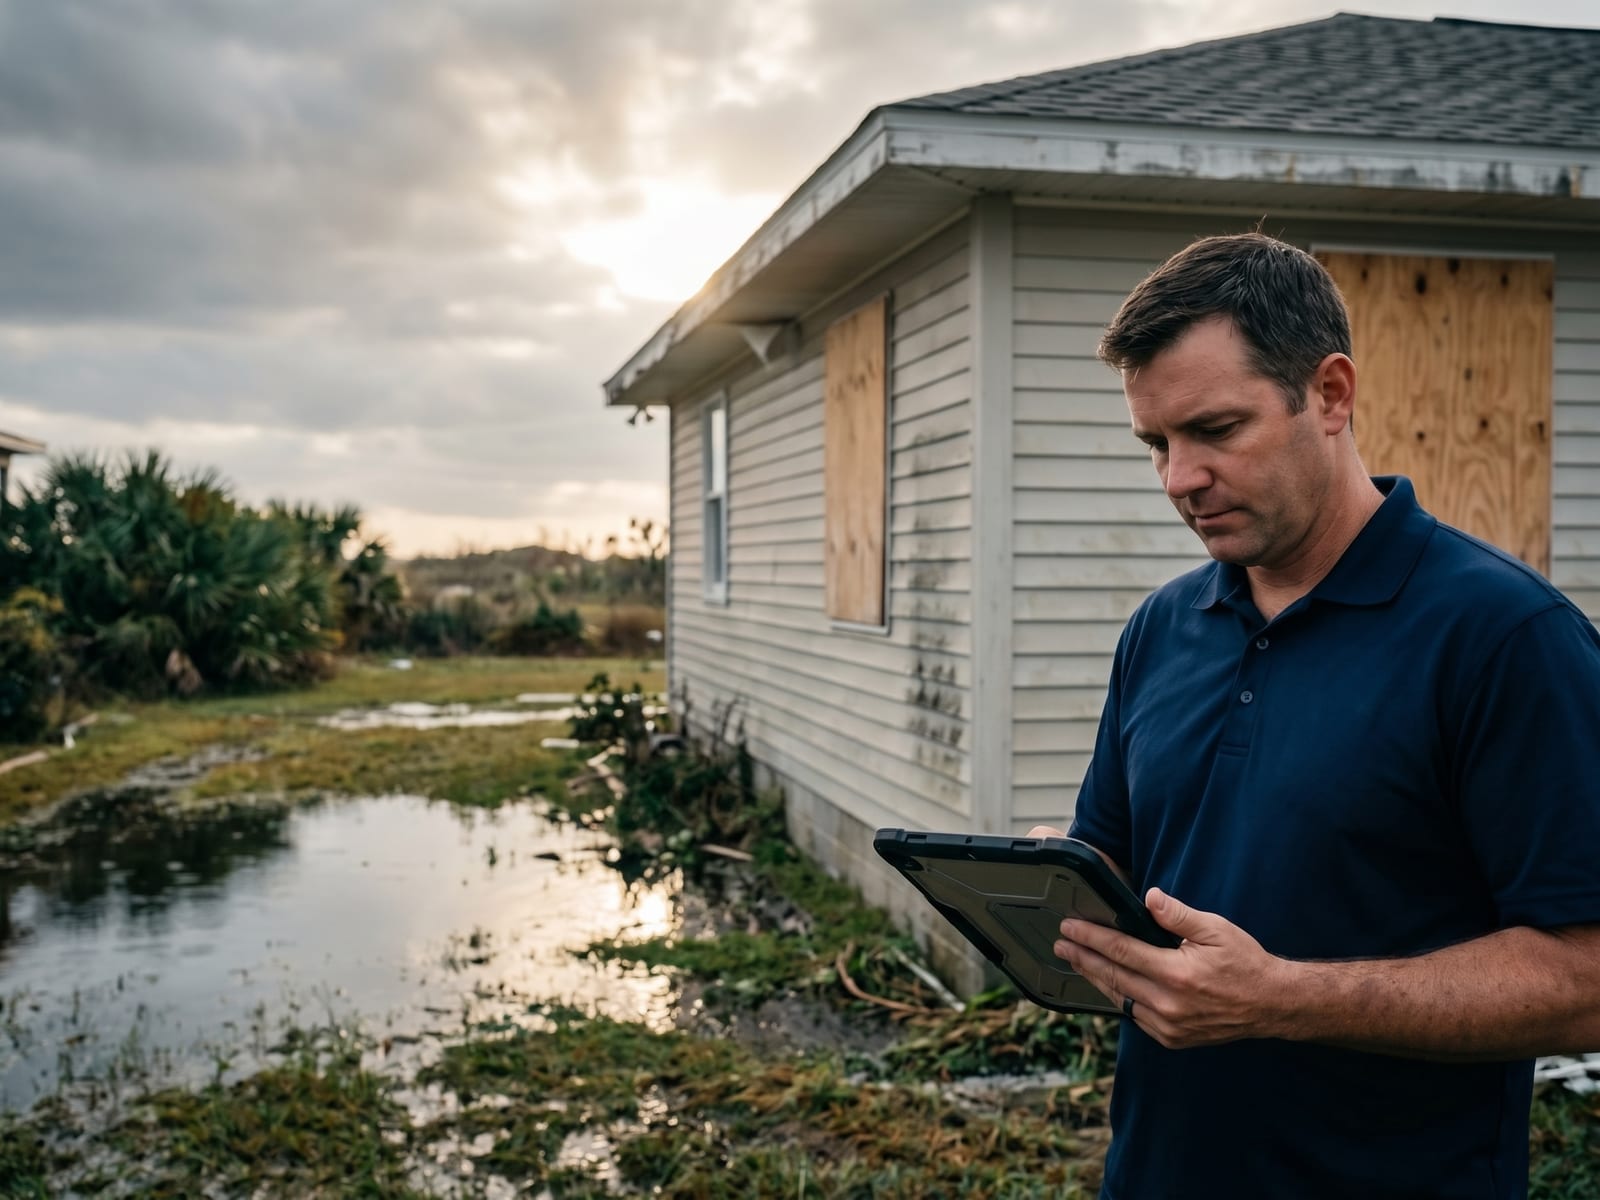
Hurricane losses are layered. We sort out what each of your policies may cover.
Wind damage
Wind damage to the roof, siding, windows, and doors
Wind-driven rain
Rain that entered through wind-created openings
Surge and flood
Storm surge or flood damage, which needs separate flood coverage
Detached structures
Fences, docks, screened enclosures, and detached structures
Trees and debris
Fallen trees and debris
Interior and contents
Interior damage, flooring, and contents
Named-storm deductible
Your hurricane or named-storm deductible, often a percentage of coverage
ALE
ALE (Additional Living Expenses): the cost of living elsewhere while you rebuild
What To Do Right Now
You are dealing with a lot. These steps protect your safety and your claim.
Wait until it is safe. Return only when local authorities say it is safe.
Photograph everything. Take photos and video before cleanup, wind damage and water lines both.
Make safe temporary repairs. Tarp or board openings if you can, and keep every receipt.
Report to every insurer. If you have flood coverage, report to that insurer too. It is usually a separate policy.
Track your extra costs. Save receipts for lodging, meals, and temporary needs.
Call us before you accept an offer. There is no cost to review your claim.
Hurricane Damage Questions
Wind Or Flood: Why Does It Matter?
Wind damage is usually covered by a homeowners policy, while flood from rising water usually needs a separate flood policy. How damage is classified can change what is paid.
What Is A Hurricane Deductible?
Many Southeast policies use a percentage deductible for named storms. Your declarations page shows the amount and when it applies.
Can I File More Than One Claim?
Possibly, for example a homeowners claim and a flood claim, because they come from different policies. We help you sort out which apply.
What If Many Neighbors Are Filing Too?
After a major storm, insurers are busy and claims can slow down. Complete documentation ready to send can help.
How Long Does A Hurricane Claim Take?
It depends on the size of the loss and how the insurer responds. We explain the likely timeline in your free claim review.
Other Claims We Handle
Storm Damage
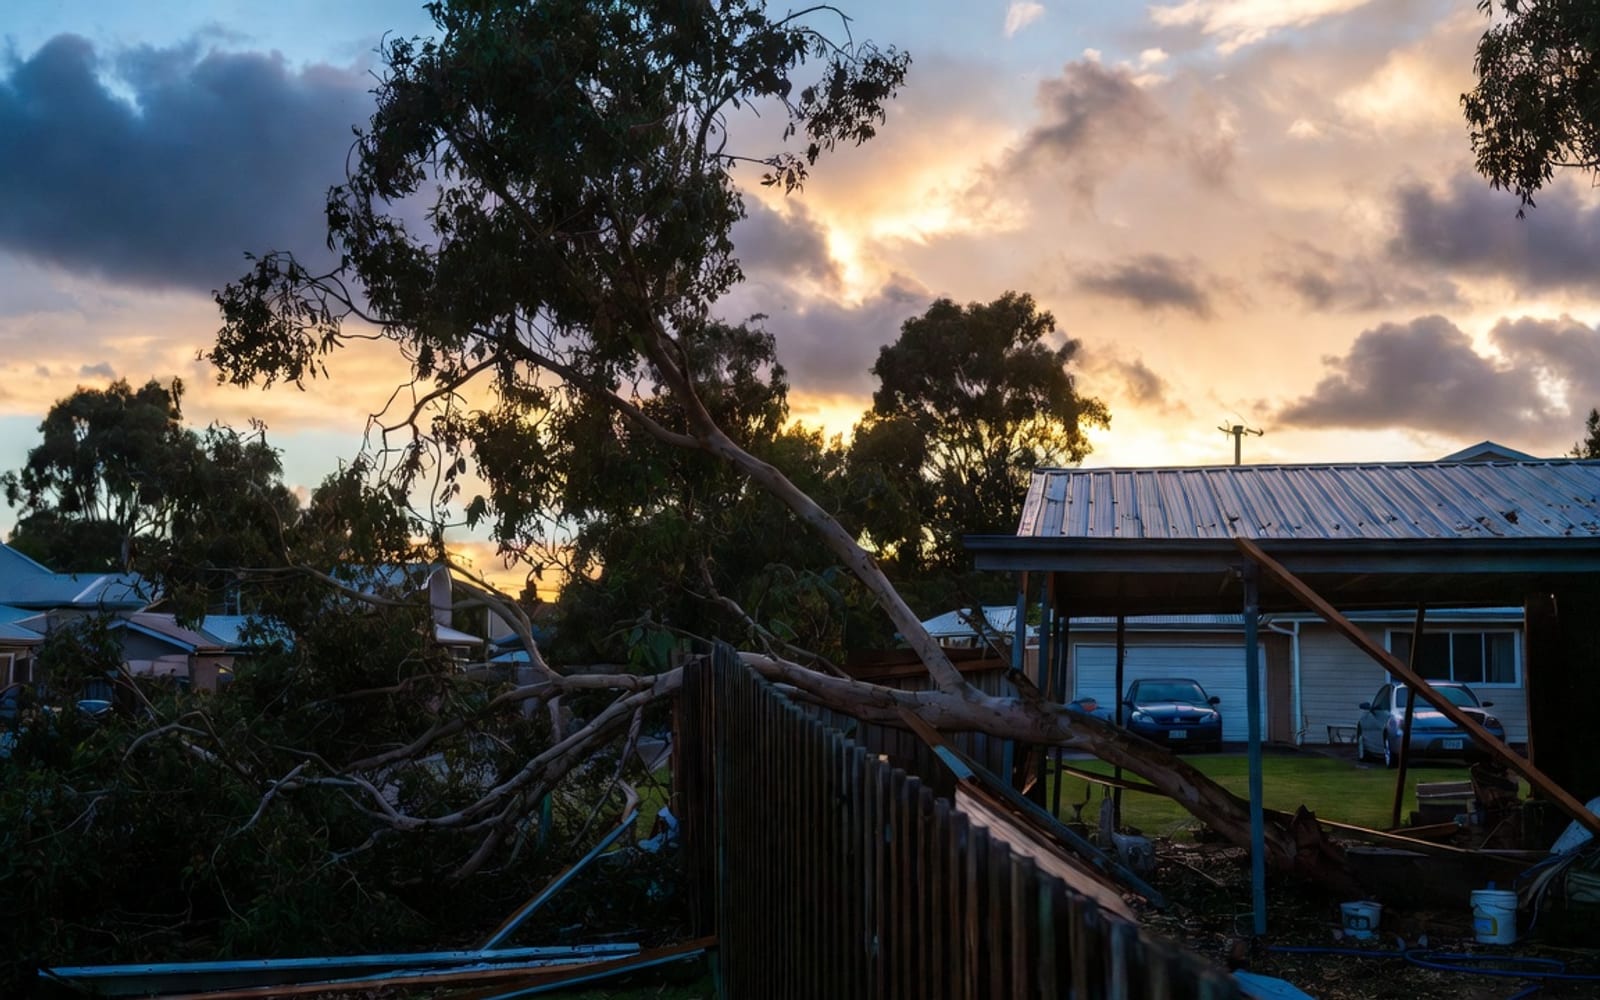
Lightning, rain intrusion, and broad damage from severe storms.
Learn More about Storm Damage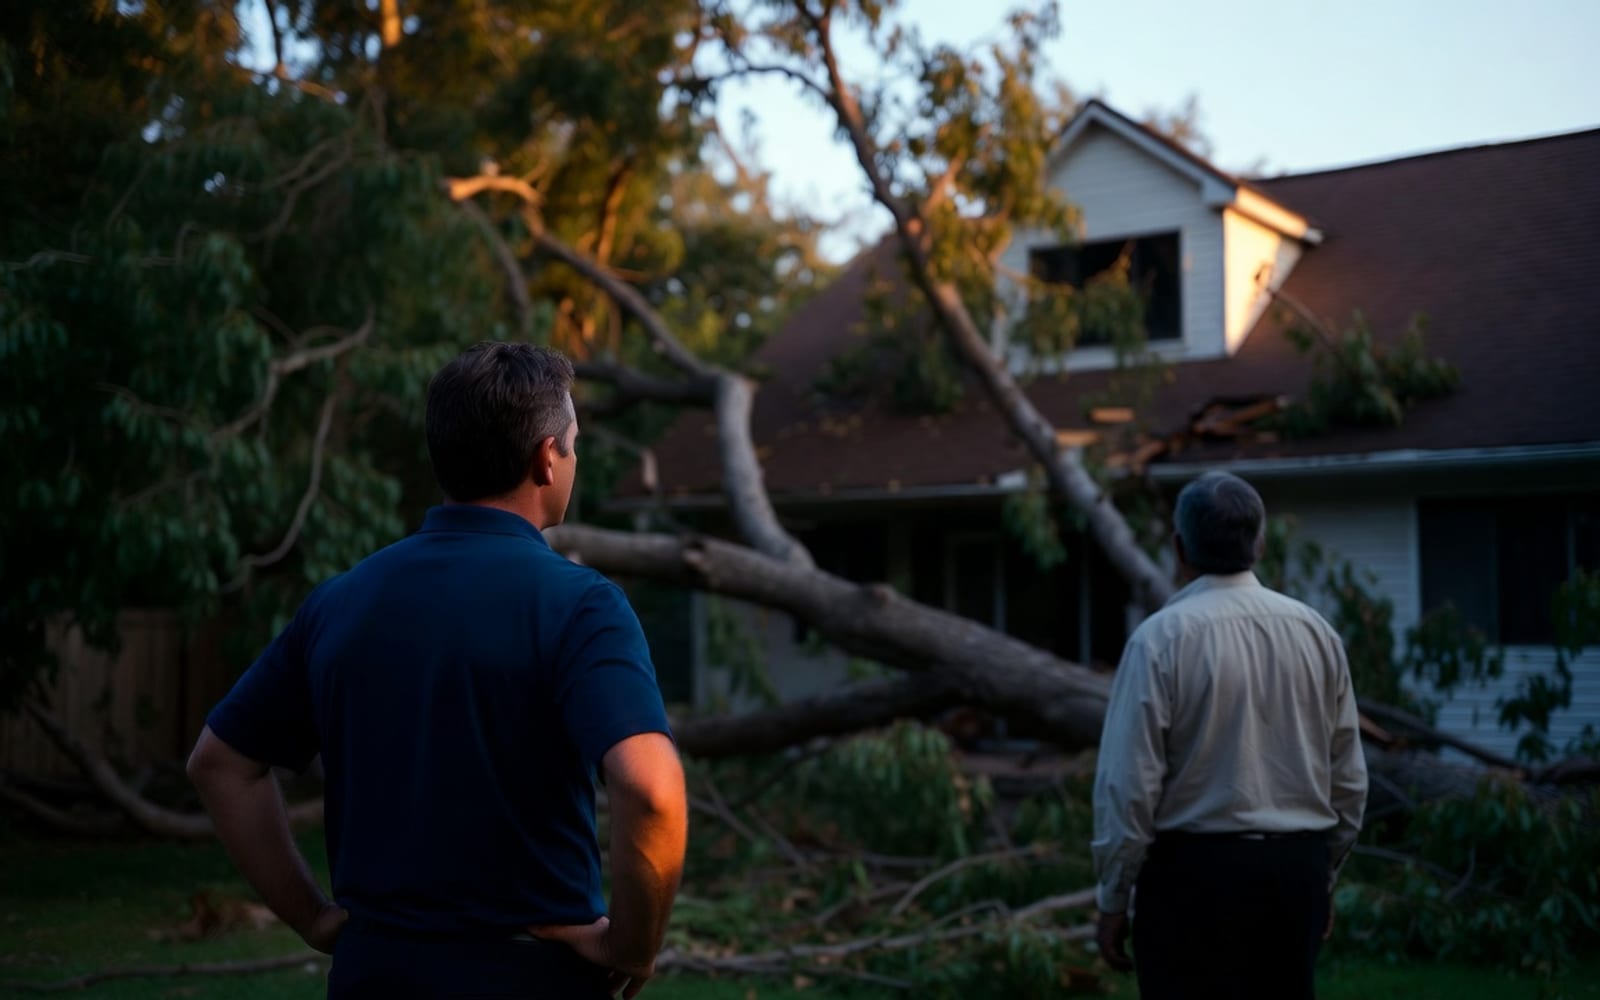
Wind Damage
Lifted shingles, torn siding, and wind-driven rain damage.
Learn More about Wind Damage
Underpaid Claims
Lowball offers, missed line items, and estimates that fall short of real repair costs.
Learn More about Underpaid Claims